Agentic-AI Equity Research

Wall Street Grade. Objective Price Targets.

Give it a ticker. You get back the research that would take weeks.

What you get back
Sample
Meta Platforms, Inc. (META)
Initiation · 11 Sep 2026
NEUTRAL / MARKET PERFORM
Price (11 Sep)US$648.03
Target PriceUS$635.00
Implied return(1.7)%
52-Week Range520.26 – 790.80
Market CapUS$1,659bn
Enterprise ValueUS$1,663bn
Prepared byThe research pipeline,
under your own byline and
branding — every source linked
Investment summary

We initiate coverage of Meta Platforms, Inc. (Nasdaq: META) with a Neutral / Market Perform rating and a 12-month price target of US$635, 2.0% below the 11 September 2026 close of US$648.03. Our target blends a ten-year discounted cash flow at a 9.64% weighted average cost of capital (50% weight, US$583 per share), trading comparables (40%, US$688) and precedent transactions (10%, US$658).

Meta is the largest digital advertising business in the world on current forecasts, with US$228.2bn of trailing-twelve-month revenue, a 48.0% trailing EBITDA margin and 3.60bn daily users. It is also, in 2026, a company spending US$137bn on property and equipment in a single year, funded partly with US$55bn of senior notes issued in November 2025 and May 2026.

The advertising franchise deserves a premium; the capital programme that surrounds it does not yet earn one.

NEUTRAL RECOMMENDATION / INITIATION OF COVERAGE
■The advertising engine is compounding faster than the market it competes in. Revenue grew 22% in FY2025 to US$200.97bn and then accelerated: Q2 2026 revenue rose 28% to US$60.80bn, with average price per ad up 12% and impressions up 14%. EMARKETER forecasts a 26.8% share of global digital ad spending in 2026, placing Meta ahead of Alphabet for the first time.
■Capital intensity, not competitive position, is what sets the valuation. Capital expenditure including finance leases is guided to US$130–145bn in FY2026, equal to 54.5% of our forecast revenue. Unlevered free cash flow is negative US$39.0bn in FY2026E before turning positive in FY2028E, so 76% of our DCF enterprise value sits in the terminal period.
■The debate is binary on whether US$137bn of annual capex earns its cost of capital. Our bear case values the shares at US$221 and our bull case at US$753; at 20/60/20 probabilities the weighted DCF value is US$543. The 2.6x spread between bear and bull is the widest of any large-cap technology franchise we cover, which is why we carry 20% of the weight outside the DCF and hold the rating at Neutral.
■Relative valuation offers support, but at the level capital intensity warrants. Meta trades on 11.9x forward EBITDA and 21.0x forward operating earnings against a peer median of 15.1x and 20.9x. Applying peer medians to our model's forward figures implies US$638–US$823 per share, and precedent transactions imply US$406–US$774.
US$m unless statedFY2023AFY2024AFY2025AFY2026EFY2027E
Total revenue134,902164,501200,966252,082295,401
Revenue growth (%)16.122.022.225.417.2
EBITDA57,92984,878101,892113,517148,426
EBITDA margin (%)42.951.650.745.050.2
Operating income46,75169,38083,27684,699104,277
Operating margin (%)34.742.241.433.635.3
Diluted EPS (US$)14.8723.8623.4930.1933.37
Free cash flow42,78952,10343,5854,47123,776
Capex incl. finance leases28,32439,22572,215137,384141,792
Capex (% of revenue)21.023.835.954.548.0
EV/EBITDA (x)15.3x17.5x15.2x11.9x10.1x
Recommendation: Neutral / Market Perform. Meta offers the best advertising growth in the top tier and the weakest free-cash-flow conversion of any mega-cap platform in 2026, because capital expenditure absorbs 54.5% of revenue. Our valuation range of US$440–US$785 spans a bear case in which the AI build never earns its cost of capital and a bull case in which capital intensity normalises while advertising growth stays near 20%. We would revisit the rating on a stated capital-intensity glide path, evidence of AI infrastructure returns, or a resumption of buybacks.
Your publication12 Sep 2026 · 8 min read

SK hynix: peak-cycle earnings, full-cycle valuation

By your name · Published under your own masthead

SK hynix is the world's leading supplier of high-bandwidth memory and the second-largest DRAM manufacturer, and it is in the most profitable period in the history of the memory industry. Revenue of W97.1tn in FY2025 has already been surpassed by W131.9tn in the first half of FY2026 alone — a period in which the second quarter printed a 76% operating margin.

PriceW1,812,000
TargetW1,600,000
Downside11.7%
EV/EBITDA4.9x

The cheapest large memory franchise on trailing multiples — which is precisely the point. The shares trade at 8.1x last-twelve-month EV/EBITDA and 8.2x trailing earnings against peer medians of 15.8x and 22.0x. But those twelve months are the peak of the cycle — W143.6tn of EBITDA against W36.0tn in FY2024 — while each peer's window straddles a different point of the same cycle. The discount is a statement about cycle position, not about franchise quality.
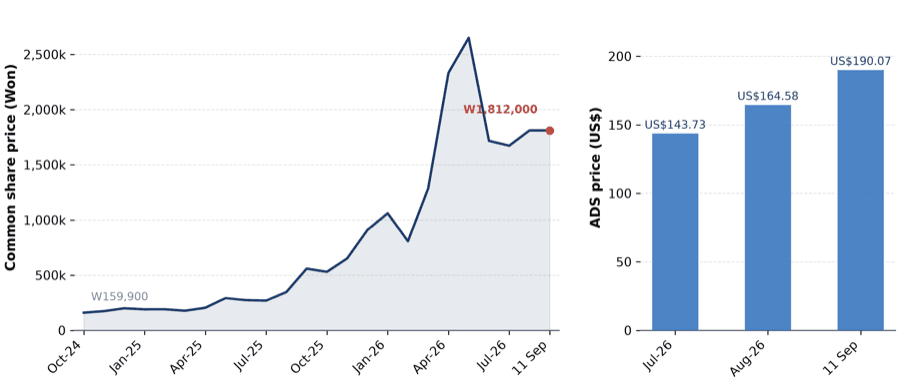
Figure 1 — Common share price (KRX: 000660) and ADS price (Nasdaq: SKHY)
SK hynix common share price on the KRX against the Nasdaq ADS line since the ADS listing in July 2026.
Source: Monthly closing prices, KRX line October 2024 – 11 September 2026 and the Nasdaq ADS line since the 10 July 2026 listing.

The valuation is a barbell, not a point. The bear case — supply additions arriving into weaker demand, revenue peaking in 2027 — is worth W976,546, some 46% below the current price. The bull case is W2,452,662, or 35% above it. Weighted 25/50/25, the probability-weighted expected value is W1,662,561, within 8% of where the shares trade. This is a high-variance stock rather than an obviously expensive one, and I would become a buyer below roughly W1,350,000.

“A US investor paying today's ADS price accepts a materially lower expected return than a Korean investor buying the identical economic interest.”

What would make me wrong. The bull case has undersupply persisting through 2028, revenue compounding at 39.7% to FY2030 and the terminal EBITDA margin holding at 72.3%. Here is what has to be true for that, and why I think the 2029 trough in my base case is the more likely shape…

Page one of a real write-up, produced 12 September 2026 and not maintained. Positions and disclosures run at the foot of every published post. Not investment advice.

A full equity research report of 40–50 pages, built on a live .xlsx model that ships with the client-ready licence.

Real pages from completed runs, shown as produced and not maintained — prices, estimates and ratings are stale by design. Not investment advice.

How it works

An agent that works like an analyst, and checks like an auditor.

You give it a ticker. It does the week.

  • Works like an analyst would. Reads all filings, models the numbers, argues the valuation, writes the research.
  • Every step is reviewed. A separate agent reviews the output of each stage, checking the files against a defined set of criteria.
  • Everything can be traced back. Every filing, transcript, and disclosure. All facts have their sources cited.

Independent agents check each other’s work. Review findings go back for correction, and unresolved issues are flagged with the research.

Watch it work on a company you know.

Enter a company, or press Run to try Apple.

Step 01 / 04Ready

Researching the company

  • Finding the filings
  • Reading earnings calls
  • Researching competitors and industry

The research process

Deep research.
Every claim checked.

One agent builds.
Another reviews.

  1. Review gate 1: independent review of company research
  2. Review gate 2: independent review of financial modeling
  3. Review gate 3: independent review of valuation analysis
  4. Review gate 4: independent review of analysis
  5. Review gate 5: independent review of report assembly
Yours to readThe finished research report is ready for you to read, with sources and any flagged issues.

Select a stage to explore

Stage 01 / 05

Company Research

Start with the evidence.

Read company filings, earnings calls and the competitive landscape to build a sourced picture of the business.

What the reviewer checks
  • Sources support the claims
  • Required research areas are covered
  • Evidence is cited and traceable

Review passesThe output feeds the next stage: model.

Reviewer finds an issueThe producing agent gets specific findings, revises the work, then submits it for another review.

At the end of the process

Your research. Your decision.

A full research report and concise write-up, with sources you can check.

None of which makes the agent infallible. It can misread a filing or carry an error forward, and Analyst Report has not had a registered analyst review the result, which is exactly why every figure stays traceable to its source and why the model behind it ships with live formulas on a client-ready note. Check the work, and make your own investment decisions. The research is not investment advice and for informational purposes only.

What it's worth

Clarity before you invest.

A clear valuation helps you decide what to buy and what to pass on.

SampleIllustrative cases, not a live track record

Based on a $10,000 position
01ConvictionBUY call

The one you bought.

$3,197

Gain captured

+32.0%Share price
Illustrative price pathNote's target
Illustrative share price rises from 2.94 to 3.88. The note's target is 4.30.
At publication
2.94
Note's target
4.30
Later price
3.88

The note put a 4.30 target on a 2.94 share and showed the fleet economics behind it. You took the position.

02DisciplineSELL call

The one you passed on.

$1,381

Loss avoided

-13.8%Share price
Illustrative price pathNote's target
Illustrative share price falls from 26.80 to 23.10. The note's target is 21.00.
At publication
26.80
Note's target
21.00
Later price
23.10

The note put a 21.00 target on a 26.80 share and showed the contract roll-offs behind it. You stayed out.

Worked examples, not published calls. No real company is named. Price moves are measured from the close at publication; cash figures assume a $10,000 position and exclude dealing costs. Not investment advice.

Why this exists
A note from the founder

Doing Equity Research takes a lot of time. It just got easier.

I am a private investor looking for an edge in the markets. To do so, I am turning over a lot of rocks. And I really mean a lot. I am looking at the most obscure opportunities.

It takes days to fully grasp an industry, understand competitors, research management, and to properly value a business.

Things just changed. My agents do the heavy lifting for me. Quite suprisingly, they even manage to uncover details that I overlooked. It speeds up my research process and helps me make better investment decisions.

Generating alpha just became easier.

Pricing

Research one company. Or your whole list.

Buy reports as you need them, with savings on larger packs. Add monthly coverage for the companies you keep following.

1 report

Bulk rates apply at 5 and 10 reports. For 25 or more, request a custom quote.

Personal

Research to inform your own view.

$29

one-time · 1 report

$29 per report

  • Detailed research report
  • 3-page write-up, exhibits and charts
  • Private use only
  • Excel model and pitch deck not included

Client-ready

Research you can publish under your name.

$199

one-time · 1 report

$199 per report

  • Everything in Personal, licensed to share
  • Full Excel model with live formulas
  • Your logo and byline on the cover
  • Pitch deck included with every report
  • Share with clients and subscribers

Choose companies when you use your reports. Packs are valid for 12 months from purchase. No subscription or automatic renewal.

Prices in USD. EU VAT is calculated at checkout from your billing address; enter a VAT number there to be reverse-charged.

Need custom branding or sponsored research?Talk to us ↗

A run that halts is never billed, and anything already charged for it comes back. Once a note is delivered, the sale is final.

Questions

The things people ask before they buy.

Is this just ChatGPT with a long prompt?
No. A run is five separate pieces of work, each graded against the files it produced by a reviewer with no memory of producing them — a word count read from the document, a balance sheet tested year by year, charts counted by listing the directory. A prompt gives you an answer. This gives you an answer plus the working, and stops when the working does not hold up.
Can I really publish it under my own name?
From the client-ready licence up, yes. The PDF, the model and the exhibits are yours to edit, rebrand and republish — to clients, to subscribers, or into your own note, with no Analyst Report logo on the deliverables and no attribution requirement. A Personal note is the same research, watermarked and meant for your own desk rather than for sending on.
What if a number is wrong?
You will be able to find it. Every claim traces to the filing, transcript or disclosure it came from, and every figure in the note traces to a cell in the model behind it. On a client-ready note that model ships with the report, which is the point of sending a spreadsheet rather than a PDF of one: you can check the number, change the assumption behind it, and watch the valuation move.
Which markets do you cover?
Anything with a public listing and public filings — US, UK, EU, ASX, TSX and most of the smaller exchanges. Coverage is limited by disclosure, not by geography: if the company files and reports, a run can be done on it.
How long does a run take?
About five hours, and it needs nothing from you once it starts. You get an email when the PDF lands.
What happens if the run fails?
It halts and tells you which step it stopped at, rather than filling the gap with something plausible. You keep the steps that finished and the files they produced, and a halted run is not billed — if it was already charged, we refund it. A run that finishes and delivers its note is final: that is the work you commissioned, and the terms explain what it is and what to check before you rely on it.
Is this investment advice?
No. It is research: an argument with its evidence attached, including the bear case argued at full strength. What you do with it is your decision and your responsibility, exactly as it would be with a sell-side note.
Can the agent get it wrong?
Yes. It reads filings the way software reads them, and software misreads things — a restated segment, an unusual accounting treatment, a footnote that changes what a number means. The checks between steps catch a great deal and are the reason a run halts rather than guesses, but they are not a guarantee of correctness, and no output here has been reviewed by a registered analyst. That is precisely why every figure links to its source, and why the model behind it ships with live formulas on a client-ready note: so you can check the work rather than take it on faith. The investment decision, and the responsibility for it, stay yours.
Do I get the spreadsheet, or just the report?
The spreadsheet comes with a client-ready note and with every note on a coverage plan. It has live formulas rather than pasted values — three linked statements, the working capital and debt schedules, and the valuation built on top of them — so you can change a driver and watch the valuation move. A Personal note is the report, the write-up and the exhibits, all at 300 DPI and yours to drop into your own deck; the model it was built on is what the client-ready licence adds.
Every figure
traced to its filing
The model
live formulas, from client-ready up
Your branding
on every client-ready note

Start with the one you keep meaning to look at.

One name, researched properly, in about five hours — and nothing for you to do while it runs.

See what a full note contains →